Get an Unsecured Business Loan in India
Are you a business owner looking for funds to expand your business but don’t want to mortgage your property or provide collateral? An Unsecured Business Loan in India could be a suitable financing option for your requirements.
Whether you run a manufacturing unit, trading business, retail shop, wholesale business or service company, access to timely finance can help you manage working capital, purchase inventory, upgrade machinery and expand your operations.
Today, several banks and Non-Banking Financial Companies (NBFCs) offer unsecured business financing to eligible entrepreneurs and business owners based on their financial profile, business performance and repayment capacity.
At Fatafatmoney.com, we help business owners explore suitable financing options based on their requirements and eligibility.
In this guide, we will explain how to get an unsecured business loan in India, eligibility criteria, required documents, interest rates and the application process.
What Is an Unsecured Business Loan?
An Unsecured Business Loan is a type of business financing that generally does not require the borrower to pledge property, land or other assets as collateral.
Unlike secured loans, where lenders take security against an asset, unsecured business loans are primarily assessed using the applicant’s credit history, business turnover, banking transactions, financial performance and repayment capacity.
These loans are commonly considered by:
- Small and medium-sized business owners.
- Traders and wholesalers.
- Manufacturers and distributors.
- Retail shop owners.
- Service providers.
- Proprietorship firms.
- Partnership firms and LLPs.
- Private Limited Companies.
The final approval and loan amount depend on the lender’s credit policy and assessment.
Benefits of an Unsecured Business Loan
An unsecured business loan can offer several advantages to eligible business owners.
1. No Property Collateral Generally Required
One of the biggest advantages is that eligible applicants can obtain financing without mortgaging their residential or commercial property.
2. Maintain Ownership of Your Assets
Business owners can explore financing without pledging eligible personal or business property as security.
3. Manage Working Capital
Use the loan amount to manage regular operational expenses, supplier payments, salaries and inventory purchases.
4. Expand Your Business
Additional funds can help you open new branches, increase production capacity, enter new markets or upgrade business infrastructure.
5. Improve Cash Flow Management
An unsecured business loan may help manage temporary financial requirements and maintain business operations.
6. Multiple Financing Options
Eligible businesses can explore different loan amounts, repayment tenures and lending institutions according to their financial profile.
Unsecured Business Loan Eligibility Criteria in India
Before applying for an unsecured business loan, it is important to understand the eligibility requirements.
Different banks and NBFCs have different lending policies. However, the following factors are commonly considered.
1. Business Vintage
Most conventional unsecured business loan products prefer businesses with an established operating history.
The minimum business vintage varies depending on the lender and loan product.
2. Annual Business Turnover
Your annual turnover is an important factor in determining your business’s financial capacity.
Higher and consistent turnover may help demonstrate business stability, although turnover alone does not guarantee approval.
3. CIBIL Score
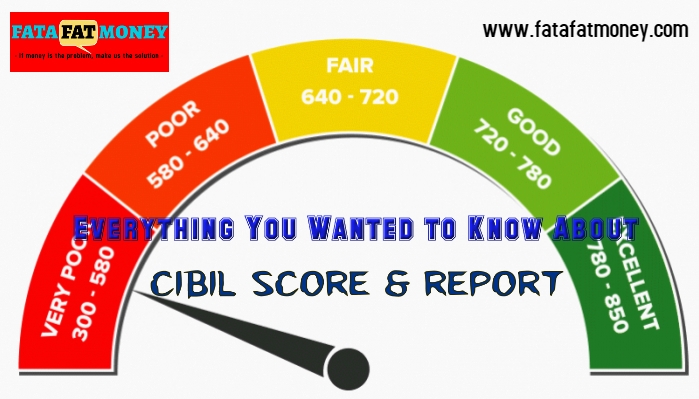
Your personal credit history and CIBIL score can play an important role in the loan assessment.
A healthy repayment track record and responsible credit utilisation can strengthen your application.
4. Banking Transactions
Lenders generally evaluate the business’s bank statements to understand:
- Monthly credit transactions.
- Average bank balance.
- Regularity of business income.
- Cheque or EMI bounce history.
- Existing loan repayments.
- Overall banking conduct.
5. Profitability and Financial Performance
Lenders may review your Income Tax Returns, profit and loss statements and balance sheets to assess the financial position of your business.
6. Existing Loan Obligations
Your current EMIs and outstanding loan obligations are also considered when evaluating repayment capacity.
Important: There is no single universal eligibility criterion for every unsecured business loan. Approval depends on the selected lender’s policies and individual credit assessment.
Documents Required for an Unsecured Business Loan
Preparing the required documents in advance can help make the application process smoother.
Here is a general list of documents that banks and NBFCs may request.
Personal Documents
- PAN Card.
- Aadhaar Card or other valid identity proof.
- Residential address proof.
- Passport-size photographs, where required.
Business Documents
- GST Registration Certificate, where applicable.
- Udyam Registration Certificate, where applicable.
- Business registration or incorporation documents.
- Business address proof.
- Partnership deed, where applicable.
- Certificate of Incorporation, where applicable.
Financial Documents
- Last 6–12 months’ business bank statements.
- Income Tax Returns, generally for the last 1–3 years, where required.
- Balance Sheet.
- Profit and Loss Statement.
- GST returns, where applicable.
- Existing loan statements and repayment details.
The exact documentation checklist depends on the lender, the applicant’s business constitution and the loan amount.
How Much Unsecured Business Loan Can You Get?
The eligible loan amount depends on several financial and business-related factors.
Banks and NBFCs generally evaluate:
- Annual business turnover.
- Average monthly banking transactions.
- Profitability and cash flow.
- Credit score and repayment history.
- Business vintage.
- Existing loan obligations.
- Financial stability of the business.
For example, two businesses with similar annual turnover may receive different loan offers because their profitability, banking conduct and existing liabilities may differ.
Therefore, it is important to evaluate your overall business profile before applying.
Unsecured Business Loan Interest Rates in India
The interest rate on an unsecured business loan varies from lender to lender.
Some of the important factors that influence the interest rate include:
- Applicant’s CIBIL score and credit history.
- Business turnover and profitability.
- Business vintage.
- Required loan amount.
- Existing financial obligations.
- Repayment tenure.
- Lender’s internal risk assessment.
Before accepting an offer, compare the following:
- Interest rate.
- Annual Percentage Rate (APR).
- Processing fees.
- Documentation or other applicable charges.
- EMI amount.
- Repayment tenure.
- Foreclosure and prepayment conditions.
Always review the lender’s Key Facts Statement (KFS), where applicable, to understand the total cost of borrowing.
How to Get an Unsecured Business Loan in India: Step-by-Step Process
Getting an unsecured business loan can become easier when you follow a structured application process.
Step 1: Identify Your Business Financial Requirements
First, determine how much funding your business needs.
Identify whether the requirement is for business expansion, inventory purchase, machinery, working capital or other operational expenses.
Avoid applying for a higher loan amount than your actual repayment capacity.
Step 2: Check Your Business Loan Eligibility
Review your business vintage, annual turnover, banking transactions, credit score and existing loan obligations.
Understanding your eligibility before applying can help you identify suitable financing options.
Step 3: Compare Banks and NBFCs
Different financial institutions have different business loan products and eligibility requirements.
Compare the available options based on:
- Loan amount.
- Interest rate and APR.
- Repayment tenure.
- Processing fees.
- Collateral requirements.
- Eligibility criteria.
Step 4: Prepare Your Documents
Keep your personal, business and financial documents ready.
Ensure that your bank statements, GST returns and financial information are accurate and updated.
Step 5: Submit Your Loan Application
Apply through the selected bank, NBFC or an appropriate loan assistance channel.
Provide accurate information about your business and financial position.
Step 6: Complete Verification
The lender may conduct financial, banking, credit and business verification before making a lending decision.
Step 7: Review the Loan Offer and Accept
If your application is approved, carefully review the sanction terms, KFS, applicable charges, repayment schedule and loan agreement before accepting the offer.
The lender will disburse the loan according to its applicable procedures.
Unsecured Business Loan vs Secured Business Loan
Understanding the difference between secured and unsecured business loans can help you select a suitable financing option.
| Parameter | Unsecured Business Loan | Secured Business Loan |
|---|---|---|
| Collateral | Generally not required | Required |
| Property mortgage | Generally not required | May be required |
| Loan assessment | Credit and business profile | Credit, business profile and security |
| Interest rate | May be higher | May be lower |
| Documentation | Financial and business documents | Financial and security documents |
| Approval | Subject to lender assessment | Subject to lender assessment |
The actual terms, rates and documentation requirements depend on the financial institution and loan product.
Can MSMEs Get a Business Loan Without Collateral?
Yes. Eligible Micro and Small Enterprises (MSEs) can explore collateral-free financing options under applicable lending policies and credit guarantee schemes.
The Reserve Bank of India’s MSME lending directions were amended on February 9, 2026. Under the updated directions, banks are mandated not to accept collateral security for loans up to ₹20 lakh extended to units in the MSE sector.
Banks may also increase the collateral-free limit up to ₹25 lakh for MSE units with a good track record and strong financial position, subject to their internal policies.
Additionally, the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) provides credit guarantee support to eligible lending institutions for qualifying collateral-free credit facilities.
However, a credit guarantee does not mean automatic loan approval. The lender still evaluates the applicant’s eligibility, repayment capacity and business profile.
Common Reasons Why an Unsecured Business Loan Application Gets Rejected
Even financially active businesses may face rejection if they do not meet the lender’s requirements.
Some common reasons include:
1. Low Credit Score: A poor credit history or frequent repayment delays may affect eligibility.
2. Insufficient Banking Transactions: Low or inconsistent business banking activity may make it difficult to demonstrate repayment capacity.
3. Existing High EMI Obligations: Multiple outstanding loans can reduce your available repayment capacity.
4. Frequent EMI Bounces: Repeated cheque or EMI bounces may negatively affect the credit assessment.
5. Incomplete Documentation: Missing or inconsistent documents can delay or affect the application.
6. Insufficient Business Vintage: Newly established businesses may not meet the operating-history requirements of conventional unsecured loan products.
7. Weak Financial Performance: Low profitability or irregular cash flow may affect the lender’s decision.
How Fatafatmoney.com Can Help You Explore an Unsecured Business Loan
Finding a suitable business loan can be challenging when different banks and NBFCs have different eligibility requirements, interest rates and documentation policies.
Fatafatmoney.com aims to simplify the financing discovery process by helping business owners explore available loan options.
With Fatafatmoney.com, you can seek assistance with:
- Exploring unsecured business loan options.
- Understanding business loan eligibility.
- Identifying potentially suitable lenders.
- Understanding documentation requirements.
- Comparing available financing options.
- Navigating the loan application process.
Whether you are a trader, manufacturer, wholesaler, retailer or service provider, understanding your financing options can help you make better business decisions.
Looking for an Unsecured Business Loan in India?
Visit https://www.fatafatmoney.com/ and explore suitable business financing options based on your requirements and eligibility.
Frequently Asked Questions About Unsecured Business Loans
1. Can I get a business loan without collateral in India?
Yes. Several banks and NBFCs offer unsecured business loans to eligible businesses without requiring property or other collateral. Approval depends on the lender’s credit policy and financial assessment.
2. What is the minimum CIBIL score required for an unsecured business loan?
There is no universal minimum CIBIL score applicable to every lender. However, a healthy credit history and good repayment track record can improve your chances of qualifying for financing.
3. Can I get an unsecured business loan for my small business?
Yes. Eligible small business owners, traders, manufacturers, retailers and service providers can explore unsecured business loan options based on their financial profile and lender requirements.
4. Is GST mandatory for an unsecured business loan?
GST documentation requirements vary depending on the business category, applicable regulations and lender policies. Some lenders may request GST registration and returns as part of the verification process.
5. Can a proprietorship firm get an unsecured business loan?
Yes. Eligible proprietorship firms can explore unsecured business financing, subject to the lender’s eligibility and documentation requirements.
6. Can I get an unsecured business loan if I already have an existing loan?
Yes, it may be possible. However, lenders consider your existing EMIs, outstanding obligations, credit history and repayment capacity before approving additional financing.
7. How long does it take to get an unsecured business loan?
Processing time varies depending on the lender, loan amount, documentation, verification and credit assessment. There is no guaranteed approval or disbursement timeline.
8. Is an unsecured business loan available for new businesses?
Some lenders offer financing options for relatively new businesses, but many conventional unsecured business loan products require an established operating history and financial track record.
9. Can I get an unsecured business loan without ITR?
Some lenders may consider alternative financial information depending on the loan product and applicant profile. However, many lenders require ITR and other financial documents to assess repayment capacity.
10. What is the difference between an unsecured business loan and a collateral-free business loan?
Both terms generally refer to financing that does not require the borrower to pledge collateral. However, specific product conditions, guarantees and lender requirements can differ.
Final Thoughts
An Unsecured Business Loan can be a useful financing option for entrepreneurs who want to expand their businesses, manage working capital or meet operational requirements without mortgaging their property.
However, selecting the right loan requires careful evaluation of eligibility, interest rates, repayment capacity, applicable charges and lender policies.
Before applying, organise your financial documents, review your credit history and compare available financing options.
If you are searching for an Unsecured Business Loan in India, connect with Fatafatmoney.com to explore suitable financing options for your business.
Fatafatmoney.com – If money is the problem, make us the solution.
Explore. Compare. Apply.
Visit: https://www.fatafatmoney.com/
Disclaimer: Fatafatmoney.com provides information and assistance in exploring loan options. Loan eligibility, interest rates, loan amounts, documentation and approval are subject to the respective bank or NBFC’s policies, verification and final credit decision. We do not guarantee loan approval, a specific interest rate or any particular loan amount.